 how-to
How to File a Claim with Bundled Insurance Policies
Last Updated: November 4, 2026
Quick Summary
To file a claim with bundled insurance policies, report the single loss to your carrier and open two separate claim files, one for each policy, since bundled policies stay separate even under one carrier. Ask for two claim numbers, confirm whether one adjuster handles both files, and keep one document folder per claim.
- Report the loss to both policies at once; one call can usually open both claim files.
- Each policy has its own deductible, coverage limits, and policy period.
- Filing one online claim and assuming it covers both policies is the most common bundling error.
- Ask in writing whether your policy applies one deductible per event or one per policy.
- Open the property claim first when home damage is the larger loss, and the auto claim the same day.
Table of Contents
- Start Here: What a Bundled Insurance Claim Involves
- Step 1: Report the Loss to Your Insurance Carrier
- Step 2: Work Through the Insurance Claim Documentation Checklist
- Step 3: How to File a Claim with Bundled Insurance Policies Online
- Does Filing a Homeowners Claim Affect Bundled Auto Insurance?
- Insurance Claim Timelines and Next Steps
- Coordinating Multi-Policy Claims and Tracking Both Files
- Get Help Filing Your Bundled Claim
- Frequently Asked Questions
Start Here: What a Bundled Insurance Claim Involves
Filing a claim with bundled insurance policies means reporting one loss to two policy files that share a single carrier and often a single agent. The claim is not one process. It is two linked processes running at the same time.
Bundled insurance is a setup where one carrier covers your home and auto under separate policies sold together, usually at a multi-policy discount. The policies stay separate. The claim files stay separate too.
One Claim, Two Policies, One Adjuster
A single event can touch both policies. A kitchen fire damages the house and the car in the driveway.
In those cases, your insurance carrier opens a property claim and an auto claim. Two claims, two deductibles, two adjusters in most cases.
Here is what matters: paying a deductible on one policy does not cover the other. Each policy has its own deductible, its own coverage limits, and its own policy period.
Step 1: Report the Loss to Your Insurance Carrier
Report the loss as soon as you can, and report it to both policies at once.
Have these ready before you dial:
- Your policy numbers for both the home and auto policies
- The date, time, and location of the loss
- A short description of what happened
Ask for two claim numbers and write both down. Then ask one direct question: "Will the same adjuster handle both files?" The answer shapes everything that follows.
If your bundled loss includes a vehicle, the auto side has its own steps. Our guide on how to file a Florida auto insurance claim walks through that process in order.
Step 2: Work Through the Insurance Claim Documentation Checklist
Documentation decides most claims. A strong insurance claim documentation checklist keeps both files moving and reduces back-and-forth with the adjuster.
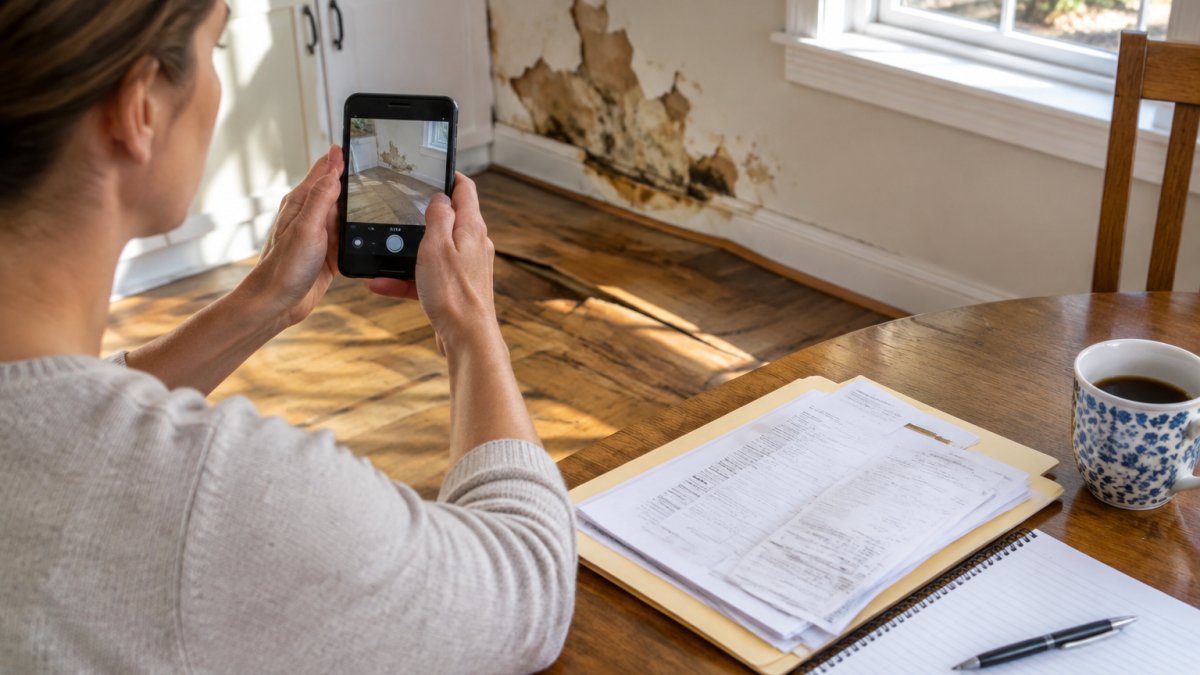
Work through this list for each policy:
- Photos and video of all damage, wide shots first, then close-ups
- A written inventory of damaged items with age and estimated value
- Receipts or proof of purchase for high-value items
Keep one folder per claim number. Do not mix them. A common mistake is sending auto receipts to the property adjuster, which slows both files down.
Property Damage and Proof of Loss
Proof of loss is a sworn statement you submit to the insurer listing the damage and the amount you are claiming. The adjuster will tell you when it is due and what form to use.
Before you sign one, confirm how your policy pays out. Our breakdown of replacement cost vs actual cash value in Florida home insurance explains which one applies to your policy before you put a figure on paper.
Step 3: How to File a Claim with Bundled Insurance Policies Online
Filing online works well for bundled policies, as long as you open two separate claims. Most major carriers let you report a loss through a policyholder portal or mobile app.
Here is the sequence we recommend:
- Log in and confirm both policies appear under one account.
- Start the property claim first and upload your photos and inventory.
- Start the auto claim as a separate filing, even if the cause is identical.
- Upload documents to the correct file, not both files.
- Save the confirmation page or email for each claim number.
Watch out: filing one online claim and assuming it covers both policies is the single most common bundling error. The second policy will sit untouched until you open it.
Does Filing a Homeowners Claim Affect Bundled Auto Insurance?
Usually no, not directly. A homeowners claim does not automatically raise your auto premium, because the two policies are rated separately and the auto policy has its own claims history.
The bundling discount is the part people often worry about. Discount terms vary by carrier, so check your policy terms rather than assuming, and ask the carrier to confirm in writing which discounts are tied to claims history and which are tied only to keeping both policies in force.
Managing Deductibles Across Both Policies
Deductible management is where bundled claims get expensive, and it is the question most policyholders ask too late.
Call Us and Get a Quote Today! →
Three variables change that math, and you need the answer to all three before you file:
- Per-policy versus per-event deductibles. Some carriers apply a single deductible when one covered event damages property insured under more than one policy. This is not universal, and it is rarely automatic. Ask the adjuster directly: "Does my policy apply one deductible per event or one per policy?" Get the answer by email.
- Windstorm and hurricane deductibles. Some home policies carry a separate windstorm or hurricane deductible expressed as a percentage of the dwelling limit rather than a flat dollar amount, so check your declarations page for the figure that applies to your cause of loss (Background on: Hurricane and windstorm deductibles). Confirm which deductible applies to the cause of loss before you assume the smaller number.
- Auto deductibles split by coverage. The auto side may carry a collision deductible and a separate comprehensive deductible. A falling limb is typically a comprehensive loss, so the comprehensive deductible applies, not collision. Confirm which coverage the adjuster is applying before you authorize repairs.
A common pattern is a policyholder who budgets for one deductible, files both claims, and then learns of the second deductible at settlement.
Watch out: do not accept a verbal "one deductible applies" from a call-center representative.
For a closer look at how bundling and deductibles interact, read how bundling insurance affects your deductible.
Insurance Claim Timelines and Next Steps
Timelines vary by carrier and by the size of the loss. What you can control is how fast you respond at each stage.
| Stage | Who Acts | What to Expect |
|---|---|---|
| Claim notification | You | Same day as the loss, if possible |
| Adjuster assessment | Carrier | Scheduled inspection after the claim opens |
| Documentation | You | Submit proof of loss by the stated deadline |
| Settlement offer | Carrier | Review the breakdown line by line |
| Claim appeal | You | File in writing if the offer falls short |
Track every deadline in your claim log. If an offer looks low, ask for the adjuster's assessment in writing and compare it to your contractor estimates before you accept.
Coordinating Multi-Policy Claims and Tracking Both Files
Multi-policy claim coordination is the gap most guides skip. Two files, two adjusters, and two sets of deadlines create real room for error, and the errors compound: a missed proof-of-loss deadline on the property file does not pause the auto file, and a settlement accepted on one claim can quietly foreclose an argument on the other. This section is the tactical part the ranking articles leave out.
Run the Two Files as One Project
Treat the bundled claim as a single project with two workstreams. Open one tracking sheet with a row per claim and these columns: claim number, policy number, adjuster name, adjuster phone and email, date opened, last contact date, next deadline, documents outstanding, current status, and settlement offered. Update it after every call, not at the end of the week.
Ask both adjusters one direct question early: "Are you sharing information with the adjuster on my other claim?" When one event caused both losses, a single set of photos, one incident report, and one contractor estimate can serve both files.
Sequence the Filings Deliberately
Filing order matters more than most people expect. Open the property claim first when the home damage is the larger loss, because the property inspection usually takes longer to schedule and the proof-of-loss deadline starts running from notification.
Watch out: do not let one adjuster close a file while the other file is still open if the two losses share a cause. A closed property claim with a signed release can limit your ability to revisit shared facts, such as the date of loss or the cause, that the auto file still depends on.
Keep the Paper Trail Clean
Keep one folder per claim number, digital or physical, and never cross-upload. Sending auto repair receipts to the property adjuster, or a contractor estimate to the auto adjuster, slows both files and creates duplicate-document confusion in the carrier's system.
Log every conversation with the date, the name of the person you spoke to, and a one-line summary of what was said. Our tips on managing multiple Florida insurance policies digitally cover how to keep both files organized in one place.
Reconcile Before You Accept
Before you accept either settlement, compare the two offers against the same evidence set. If the property adjuster credited a contractor estimate that the auto adjuster never saw, ask the auto adjuster to review it. If the auto file settled on a total-loss valuation, confirm the property file did not also claim the same items. Double-dipping is rare, but overlapping inventories are not, and carriers do reconcile the two files at the end of a bundled claim.
Get Help Filing Your Bundled Claim
Two claim files, two deductibles, and one event is a lot to manage while your home or car is damaged. Dehlinger Insurance can help you work through it.
Dehlinger Insurance has served Florida residents for over 38 years. We work with multiple top insurance carriers, which means we can review your policy terms, confirm how your deductibles apply, and help you keep both claim files moving.
Ready to hand off the paperwork? Contact our Orlando office and get a real person on your claim.
Frequently Asked Questions
How do I file a claim with combined insurance?
Call your insurance carrier's claims line or use its app and report the loss under the policy that covers the damaged property. If a single event, such as a fire or storm, damaged both your home and a vehicle, tell the representative that you hold bundled insurance so one claims adjuster can coordinate both files. You will receive a claim number for each policy. Keep those numbers, the adjuster's name, and every document you submit in one folder, because a bundled claim moves through two policy periods and two sets of coverage limits at once.
Does filing a claim on one bundled policy affect my other policy?
Usually not directly. A homeowners claim is paid from the homeowners policy and does not draw down the auto policy's coverage limits. What can change is your overall claims history and risk assessment at renewal, which the carrier may review across all policies. A single claim may also affect a multi-policy discount if the carrier re-rates the bundle. Ask your insurance agent to confirm how your carrier treats a claim on one policy when the policies are bundled, and get the answer in writing before you file.
What documents do I need before I call the insurance company?
Have your policy numbers, the date and time of the loss, photos or video of the damage, a list of damaged items with receipts or estimates, any police or fire incident report number, and contact details for anyone who witnessed the event. For a home claim, add contractor estimates and proof of loss forms the carrier requests. For an auto claim, add the other driver's information and a copy of the incident report. Complete documentation shortens the adjuster assessment and reduces back-and-forth during claims processing.
What should I avoid saying when I speak with an insurance company?
Do not guess at the cause, speculate about the cost, or say the damage is minor before an adjuster assesses it. Avoid statements that accept blame for an incident, and do not sign a release or agree to a settlement before you have the adjuster's written estimate and have reviewed your policy terms. Stick to facts you can document: what happened, when, and what was damaged. If you are unsure about a question, say you will follow up rather than offering an estimate you cannot support.
Filing a bundled claim is manageable when you treat it as two files from day one. If you would rather not juggle adjusters alone, Dehlinger Insurance can review both policies, explain your coverage limits, and help you submit clean documentation the first time. Get started with Dehlinger Insurance and file your bundled claim with confidence.