 how-to
What Is a Florida Insurance Premium Discount?
Table of Contents
- What Is a Florida Insurance Premium Discount?
- Florida Homeowners Insurance Discounts You Can Claim
- Wind Mitigation Inspection in Florida: The Discount Trigger
- Florida Hurricane Mitigation Discounts and the My Safe Florida Home Program
- How to Run a Florida Home Insurance Rate Comparison
- Steps to Qualify for a Discount on Your Policy
- Conclusion
- Frequently Asked Questions
Last Updated: October 13, 2026
What Is a Florida Insurance Premium Discount?
If you have ever wondered what is a florida insurance premium discount, it is a reduction in your policy price that you earn by proving your home or car is less likely to be damaged than the average risk. Insurers reward safer roofs, newer wiring, impact windows, and clean driving records with lower rates. At Dehlinger Insurance, we have spent over 38 years helping Florida residents find every discount their policy allows. Mitigating potential storm damage through installing impact windows serves as a primary method for securing these long-term financial incentives while simultaneously fortifying your property against the elements.
The math is simple once you see it. Your premium starts with a base rate. The carrier then adds surcharges for risk factors and subtracts credits for protective features.
Credits vs. Surcharges: How the Math Actually Works
A credit lowers your base premium. A surcharge raises it. Both apply to the same starting number, so a single missed credit can cost you year after year.
Here is how the pieces stack up:
- Base rate: the starting price for your home type and location
- Surcharges: added for claims history, roof age, or coastal exposure
- Credits: subtracted for wind mitigation features, security systems, and loyalty
- Net premium: what you actually pay
Say your base rate is set, and you qualify for two credits. Each credit trims a set percentage off the base. Skip the inspection that proves those features, and you pay full price. That is the whole game. The discount is not automatic. You have to document it.
Florida Homeowners Insurance Discounts You Can Claim
Common Florida homeowners insurance discounts fall into a few buckets. Knowing them before you shop gives you real use.
- Wind mitigation credits: for roof shape, roof covering, and how the roof attaches to the walls
- Impact-resistant windows and doors: proof that glass will not shatter in a storm
- Hip roof credit: a hip roof shape handles wind better than a gable roof
- Security and alarm credits: burglar alarms, smoke detectors, and water leak sensors
- Age-of-home credits: newer construction often earns a lower base rate
- Loyalty and bundle credits: combining home and auto, or staying claim-free
- Auto discounts: safe-driver, multi-car, and paid-in-full credits
Each carrier sets its own credit amounts. Two insurers can offer wildly different credits for the same roof. That is why a rate comparison matters so much in this state.
Wind Mitigation Inspection in Florida: The Discount Trigger
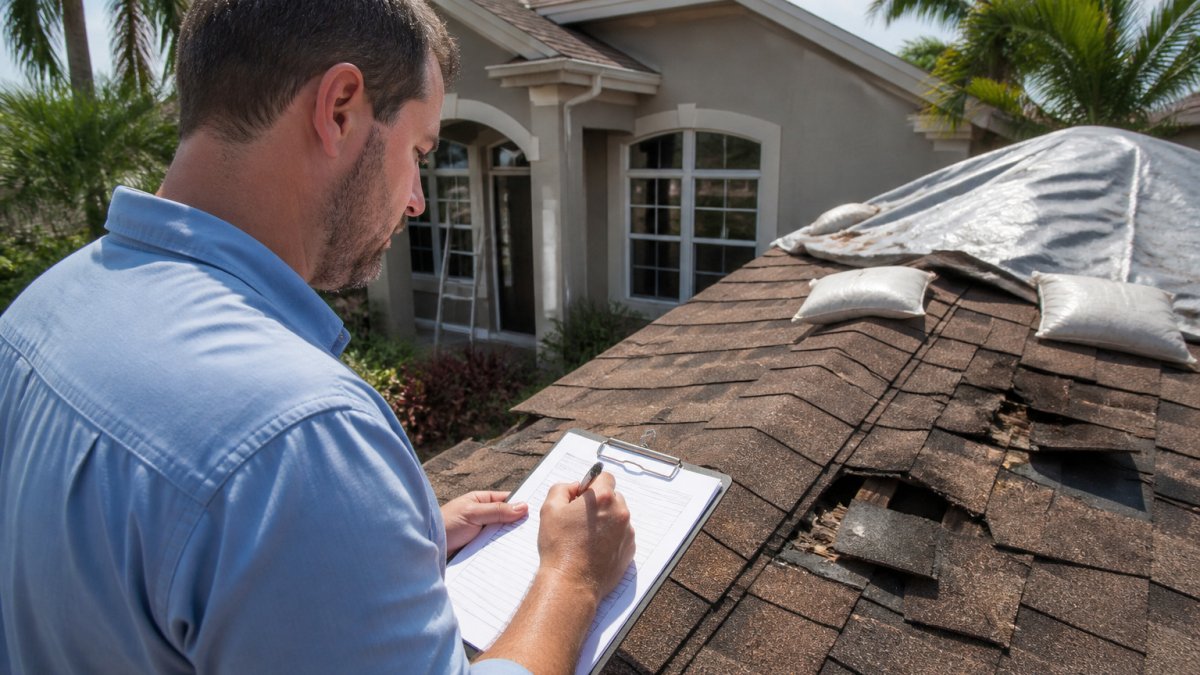
A wind mitigation inspection in Florida is the single most valuable document most homeowners can get. It is a report from a licensed inspector that confirms which storm-resistant features your home has. Without it, the insurer assumes the worst and charges accordingly.
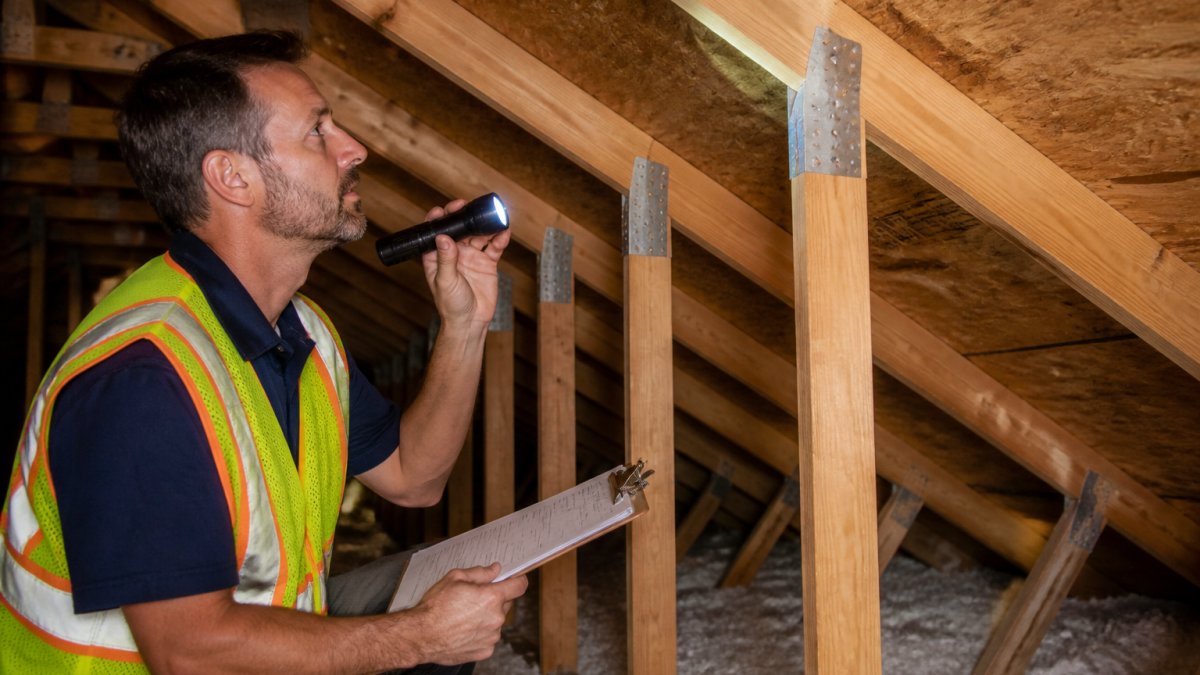
The inspection is not a home inspection. It does not judge your home's condition. It only records features that reduce wind damage.
What the Inspector Documents
The inspector checks specific items and photographs each one:
- Roof covering type and age
- Roof deck attachment method
- Roof-to-wall connection, such as straps or clips
- Roof shape, hip versus gable
- Secondary water barrier under the roof
- Opening protection, like impact glass or shutters
Get this report, hand it to your carrier, and ask them to re-rate the policy. Many homeowners find their premium drops once the credits are applied. The catch is timing. If your roof is old, the report may not help much, and some carriers will not write the policy at all.
Florida Hurricane Mitigation Discounts and the My Safe Florida Home Program
Florida hurricane mitigation discounts reward homes built or retrofitted to stand up to storms. The stronger the construction, the bigger the credit.
Call Us and Get a Quote Today! →
The state has also run a grant program to help homeowners harden their homes and, in turn, lower their premiums (Grant Application Jump Page). Program funding, eligibility rules, and grant amounts change from year to year, so check the official state source for current details before you apply. Florida Division of Emergency Management on hurricane mitigation
The logic behind these programs is straightforward. A home that survives a storm costs the insurer less. That savings gets passed back as a discount.
How to Run a Florida Home Insurance Rate Comparison
A Florida home insurance rate comparison is the fastest way to see whether you are overpaying. The same house, the same coverage, and the same address can produce very different quotes from different carriers.
Here is how to compare without wasting a weekend:
| Step | What You Do | Why It Matters |
|---|---|---|
| 1 | Gather your wind mitigation report | Unlocks credits before quotes are run |
| 2 | List your coverage limits and deductible | Keeps quotes apples-to-apples |
| 3 | Get quotes from multiple carriers | Rates vary widely by company |
| 4 | Compare the net premium, not the base | Credits change the final number |
| 5 | Check the deductible and exclusions | A cheap quote can hide thin coverage |
A lower premium with a sky-high deductible is not a win. Read the whole offer.
Steps to Qualify for a Discount on Your Policy
Qualifying comes down to proof and timing. Work through these steps in order.
- Order a wind mitigation inspection from a licensed inspector.
- Collect documentation for alarms, impact windows, and updates.
- Send the paperwork to your agent or carrier.
- Request a re-rate on your current policy.
- Ask what else you qualify for, such as bundle or loyalty credits.
- Re-shop every renewal if your rate climbs.
A common mistake is assuming your agent already has your inspection report. They often do not. Send it again and confirm it was applied.
Conclusion
Finding every discount takes effort, and most homeowners never see the full list. Dehlinger Insurance brings over 38 years of experience, relationships with multiple top carriers, and specialized coverage for older and high-value homes. Call us and get a quote today.
Frequently Asked Questions
What is an insurance premium discount?
It is a reduction applied to your base premium when your home or vehicle meets certain risk-reducing conditions. On a Florida policy, the insurer starts with a base rate, then subtracts credits for things like a hip roof, impact-rated windows, or a wind mitigation inspection report. A discount is not a coupon; it is a permanent adjustment to how the carrier prices your specific risk, and it stays on the policy as long as the qualifying feature remains in place.
Do all Florida insurers offer the same discounts?
No. Each carrier files its own rating plan with the Florida Office of Insurance Regulation, so the credits, percentages, and eligible features differ from company to company. One insurer may give a larger credit for a hip roof while another weights window protection more heavily. That is why a Florida home insurance rate comparison matters: the same home can produce noticeably different premiums depending on which credits a carrier recognizes and how much weight it assigns to each one.
Can a wind mitigation inspection reduce my homeowners insurance premium?
Yes, and it is one of the most reliable discounts available. A licensed inspector documents your roof shape, roof covering, roof-to-wall attachment, secondary water barrier, and opening protection. The completed OIR-B1-1802 form goes to your insurer, which then applies the credits your construction actually earns. Even a home built in the 1990s can qualify for meaningful credits if the roof has been updated or the openings have been protected since construction.
Can discounts be combined on a Florida homeowners policy?
Most carriers allow multiple credits to stack, but not all of them, and some have caps on the total reduction. A wind mitigation credit, a hurricane mitigation credit, a claims-free credit, and a bundling credit can often appear on the same policy. Ask your agent which credits your carrier permits together and whether any of them cancel each other out. The order in which credits are applied can also change the final number.